Blog
How to Approach European Asset Allocation: From Residency Needs to Real Asset Management
10 Sept 2026, 10:00
1. What Is European Asset Allocation, and Why Is It More Than Simply “Buying Assets in Europe”?
When people think about European asset allocation, the first things that often come to mind are buying property in Europe, investing in a fund, or simply moving part of their capital into the region. Yet many investors begin from a very different starting point. They may initially be considering European residency, their children’s education, or future living arrangements, only to realize as their plans take shape that a substantial amount of capital is about to be invested in Europe.
At that point, the question shifts from “How do I achieve a residency or family planning goal?” to something much more practical: Where should this money actually be invested? Should it go into a fund or real estate? How long will it need to remain invested? Where will the returns come from? And if the family needs the money several years from now, how easily can the investment be exited?
This is where European asset allocation really begins.
The purpose of asset allocation is not simply to identify which asset offers the highest return. It is about understanding the role that different assets play within an overall investment portfolio. The same amount of capital could be concentrated in a single real estate project or diversified across property, investment funds, equities, bonds, and other asset classes. Each approach has a different return profile, level of market risk, liquidity, investment horizon, and exit mechanism.
For cross-border investors, asset allocation also needs to be viewed within the broader global economic and macroeconomic environment. Asset prices do not move in isolation. Interest rates, inflation, exchange rates, economic growth, and industry cycles can all affect the risk and return characteristics of different investments.
Changes in European interest rates, for example, affect not only the returns available from bonds and other fixed-income assets, but also the financing costs faced by businesses and real estate projects. Higher inflation can increase construction, labour, and operating costs while reducing the real return on certain investments. Movements in the euro against other currencies can also directly affect the returns that cross-border investors ultimately receive when measured in their home currency. At the same time, differences in demographics, industrial development, economic growth, and property cycles across European countries can shape the long-term performance of local companies, funds, equities, and real estate.
Asset allocation is therefore not a one-off decision that can simply be made and forgotten. As the macroeconomic environment changes, so does the relationship between risk and return across different asset classes. Investors need to continually assess where interest rates are in the cycle, how inflation is affecting real returns, how valuations and growth prospects are evolving across markets, and whether their existing portfolio still reflects their risk tolerance and long-term objectives.
For investors who already hold significant assets in Asia, US dollars, or other markets and currencies, allocating capital to Europe is ultimately about reconsidering the structure of a global portfolio: geographic diversification, currency exposure, asset classes, investment horizons, liquidity, and sources of risk. The key question is what role European assets should play within the family’s broader wealth structure.
Before looking for a specific European fund, property, or investment product, the more important questions are therefore not simply “What can I buy in Europe?” but rather: Why should I allocate capital to Europe? What do I want this part of my portfolio to achieve? And how should it complement the assets I already own?
2. Why Are More Investors Paying Attention to European Asset Allocation?
For global investors considering European assets, an important question is: when a family’s wealth is already distributed across different countries, currencies, and investment markets, what role can Europe play within the overall asset structure?
This is also a question that AsiaEuro Group frequently encounters when working with Asian investors. Some families initially turn their attention to Europe because of European residency planning, their children’s education, or future living arrangements, while others are simply looking for new geographic markets and asset allocation opportunities. Regardless of the starting point, however, once an investment is actually made, the assessment ultimately comes back to the fundamentals of the assets themselves.
(1) Europe Offers More Than Just Another Investment Market
If a family’s wealth remains heavily concentrated in a single country, economy, or currency over the long term, the performance of its assets may also be more exposed to the same economic cycle, monetary policy environment, and exchange-rate fluctuations.
Europe does not move entirely in sync with Asia or the United States in terms of economic structure, industry cycles, and monetary policy. Allocating a proportion of a family’s portfolio to European and euro-denominated assets can therefore provide greater diversification across regions, currencies, and economic cycles.
However, diversification is not simply about “investing in more countries.” If a European fund and a European property are both ultimately highly exposed to the same country, industry, or real estate cycle, they may appear to be two different investments while still sharing many of the same underlying sources of risk.
(2) Access to Different Types of Investment Opportunities
Europe also offers a diverse range of asset classes and investment channels. In addition to publicly traded assets such as equities and bonds, real estate, infrastructure, private equity, venture capital, and various types of investment funds all form important parts of the European investment landscape. These assets differ in their sources of return, investment horizons, and risk characteristics, giving investors more options when constructing a diversified portfolio.
This is also why, when AsiaEuro Group participates in fund management and real estate investment, we look beyond the investment vehicle itself to examine the underlying assets into which capital is ultimately deployed and how those assets are expected to create value. Later in this article, we will explore this process in greater detail through actual fund structures and real estate projects.
(3) Aligning Asset Allocation with Family Needs
For cross-border families, asset allocation is often about more than investment alone. It also needs to be considered alongside the family’s plans for the coming years. Some families may already be planning for their children to study in Europe, while others may be considering long-term residence, purchasing property, or gradually establishing stronger personal and business connections in Europe. In such cases, part of the family’s future expenditure is likely to be denominated in euros, and these changes should also be taken into account when planning asset allocation.
For example, if a child is expected to study in Europe in two or three years, the family may face ongoing euro-denominated expenses such as tuition fees, accommodation, and living costs. If most of the family’s available capital has already been committed to long-term, relatively illiquid investments, even an otherwise attractive investment may not align with the family’s actual timeline for using those funds.
For these families, allocating assets to Europe therefore requires consideration not only of investment returns, but also of where the family expects to live, where their children may study, when funds will be needed, and how much liquidity should be maintained. When investment horizons, asset currencies, and future family arrangements are properly aligned, European asset allocation can become a meaningful part of a family’s long-term planning.
3. What Market Variables Should Investors Consider When Allocating Assets in Europe in 2026?
Once we decide to invest in the European market, the first step is not to immediately look for the product offering the highest return, but to understand the market environment into which the capital is about to be deployed.
For AsiaEuro Group, whether evaluating investment opportunities at the fund level or participating in the development and operation of real estate projects, interest rates, inflation, financing costs, the euro exchange rate, and local real estate cycles are not simply abstract macroeconomic indicators. They can have a direct impact on the underlying assets.
In 2026, the macroeconomic environment surrounding European asset allocation is not moving in a single direction. Interest rates, inflation, exchange rates, economic growth, real estate prices, and EU policies are simultaneously shaping the risk-return profiles of different assets. These variables do not affect every asset in the same way. Instead, they influence asset valuations, cash flows, financing costs, and expected returns through different channels.
- European interest rate environment: As of September 2026, the European Central Bank (ECB) deposit facility rate stands at 2.25%, while the main refinancing operations rate is 2.40%. Changes in interest rates directly affect bond yields and also influence corporate investment and real estate development through financing costs. For real estate projects, interest rates are more than just figures announced by the central bank. Changes in financing costs can ultimately affect development costs, project profitability, and potential returns.
- Inflation: Preliminary Eurostat data show that the euro area annual inflation rate rose to 3.3% in August 2026, up from 2.9% in July, with energy prices increasing by 14.3% year-on-year. Inflation can affect the real returns on investments and may also feed through to corporate profitability and real estate development costs through higher energy, labour, and raw material costs.
- Euro exchange rate: On 2 September 2026, ECB reference rates were approximately EUR 1 = USD 1.1578 and CNY 7.7822. For investors whose wealth is primarily measured in US dollars, RMB, or other Asian currencies, movements in the euro can amplify or reduce investment performance when returns are ultimately converted back into their home currency, even when the European asset itself generates a positive return.
- Economic growth: In the second quarter of 2026, GDP increased by 0.4% quarter on quarter in the euro area and 0.5% in the EU, indicating continued economic expansion. However, growth rates vary considerably across countries and industries. From an asset allocation perspective, Europe should therefore not be treated as a single, uniform market. National economic structures, industry competitiveness, and local demand can all influence the performance of companies, funds, and real estate assets.
- Real estate cycle: According to Eurostat, house prices increased by 4.7% year on year in the euro area and 5.1% in the EU in the first quarter of 2026, while rents also continued to rise. Changes in property prices can affect asset valuations, acquisition costs, and potential exit values, while interest rates and financing conditions can further influence the actual returns generated by real estate investments.
- EU policy and regulatory environment: In 2026, the EU continues to advance policies aimed at strengthening the Single Market, improving competitiveness, and simplifying regulation. The “One Europe, One Market” roadmap, for example, aims to further deepen Single Market integration by the end of 2027, while the EU is also working to reduce regulatory burdens on businesses and improve the environment for cross-border operations. For investors, these policy developments may affect business investment, capital flows, tax compliance, and the efficiency of investing across European markets.
We pay attention to these macroeconomic variables not to predict which market will rise next, but to understand the underlying foundations on which the returns and risks of an investment are built.
Ultimately, the impact of these factors is reflected in specific assets. Even within real estate, different projects are driven by different sources of demand. The Braga student accommodation project is supported by long-term demand for housing around universities, while the Oeiras serviced apartment project serves a different mix of residents and users, including young professionals, digital nomads, employees of nearby companies, and business travellers. The macroeconomic environment provides the broader investment context, but understanding what truly determines a project’s value requires looking deeper into the underlying asset itself.
4. What Are the Main Ways to Allocate Assets in Europe?
Europe has mature and diversified financial and real asset markets. European asset allocation therefore does not simply mean buying property or investing in funds. Depending on an investor’s risk tolerance, available capital, investment horizon, and liquidity needs, different asset classes can be selected individually or combined within a broader portfolio.
Common approaches to European asset allocation include:
| Investment Type | Key Characteristics | What to Consider |
|---|---|---|
| Equities and ETFs | Exposure to European listed companies and industries through public markets, generally with relatively high liquidity | Corporate earnings, market valuations, economic cycles, and price volatility |
| Bonds and Fixed-Income Assets | Includes government and corporate bonds, with a greater focus on interest income and relatively stable cash flows | Interest-rate movements, credit risk, investment duration, and inflation |
| Investment Funds | Professionally managed vehicles that invest according to a defined strategy across underlying assets such as equities, bonds, real estate, and private equity | Fund manager, investment strategy, underlying assets, fees, investment horizon, and exit mechanism |
| Real Estate and Related Investments | Investors may directly own residential or commercial property or gain indirect exposure through vehicles such as real estate funds | Location and market demand, rental and operating cash flow, financing and operating costs, liquidity, and exit strategy |
| Private Equity and Venture Capital | Primarily invests in unlisted companies or growth-stage projects, typically with longer investment horizons and lower liquidity | Quality of the underlying investment, business growth, fund management capabilities, and eventual exit |
| Infrastructure and Other Alternative Assets | Includes sectors such as energy, transport, logistics, and data centres, with return drivers that may differ from traditional equities and bonds | Underlying projects, investment structure, cash-flow stability, and market conditions |
There is therefore no single standard portfolio for European asset allocation that is suitable for every investor. Equities and bonds are more closely associated with public markets, real estate is more directly linked to tangible assets, while private funds may invest in companies or projects over longer investment horizons. Each asset class can therefore play a different role within a portfolio.
In the cross-border investments that AsiaEuro Group works with, funds and real estate are also two areas that require particular attention. Direct real estate investment is relatively straightforward: investors can usually assess the specific property, its location, and its rental performance. Fund investment, however, adds another layer of structure. Investors subscribe to units or shares in a fund, but the actual investment performance ultimately depends on how the fund manages its capital, which underlying assets it selects, and how those assets generate returns.
This leads to a very practical question: once capital enters a European investment fund, where does it actually go?
To answer this question, we need to temporarily look beyond the fund’s name and expected return and examine how the fund actually operates from within. In the next section, we will use fund structures in which AsiaEuro Group has participated to trace the investment process from the moment capital enters the fund and follow how it is ultimately connected to the underlying assets.
5. How Does European Fund Investment Actually Work? Understanding How Capital Reaches Underlying Assets Through AsiaEuro Group’s Fund Structure
For investors who are new to funds, the most common question is often not “What return does the fund offer?” but something more fundamental: What exactly am I investing in? Where does my capital go after it enters the fund? Who manages it? To answer these questions, it is first necessary to understand how a fund operates at a basic level.
In its simplest form, a fund connects investors with underlying assets. Investors contribute capital by subscribing to units or shares in the fund. The fund management company then invests and manages that capital in accordance with the fund’s established investment strategy, allocating it to companies, projects, or other assets that fall within the fund’s defined investment scope.
Taking AsiaEuro Group’s fund activities in Portugal as an example, Golden Meridian, a fund management company within the Group, carries out fund management activities under the regulatory framework of the Portuguese Securities Market Commission (CMVM). The role of a fund management company is not simply to “hold investors’ money.” Its responsibilities include identifying and evaluating investment opportunities in accordance with the strategy established in the fund documentation, making investment decisions, continuously managing the investment portfolio and associated risks, and arranging subsequent disposals and exits in line with the investment strategy.
The custody of fund assets and the management of investments are also not performed by the same entity. Funds typically involve a depositary, an auditor, and other professional service providers, each with distinct responsibilities for areas such as asset safekeeping, oversight, and auditing. Therefore, when an investor subscribes to a fund, the capital first enters a fund governance structure with clearly defined roles and responsibilities, rather than being transferred directly to a specific project.
However, understanding a fund cannot stop at this level.
Some fund investments are ultimately connected to specific underlying assets. In the case of real estate-related investments, once capital enters a project, the investment outcome depends on more than the investment decisions made at the fund level. It is also influenced by the project’s location and market demand, development and construction, cost control, subsequent operations, and eventual exit.
Returns from real estate-related investments may come from asset appreciation generated through development, cash flow produced through operations, and gains realised through the eventual sale or disposal of the asset. The way value is created can also vary from project to project: some projects are more development-driven, others rely more heavily on long-term operations, while some may go through the entire cycle from development to operation and ultimately to exit.
A fund investment therefore connects investors to a much longer value chain:
Investor → Fund → Investment Decision → Underlying Asset → Development & Operations → Asset Exit → Investment Return
A fund serves as the investment vehicle connecting investors with underlying assets, but the actual process of value creation ultimately takes place within those underlying assets.
6. From Real Estate Development to Asset Operations: How AsiaEuro Group Participates Across the Full Lifecycle of Real Assets
Once fund capital is further deployed into real assets such as real estate, investment returns ultimately need to be realised through the development, operation, and value enhancement of actual projects. AsiaEuro Group’s involvement does not stop at the investment stage. The Group also participates in real estate development, construction, and subsequent operations, extending asset management into the day-to-day operation of the underlying projects.
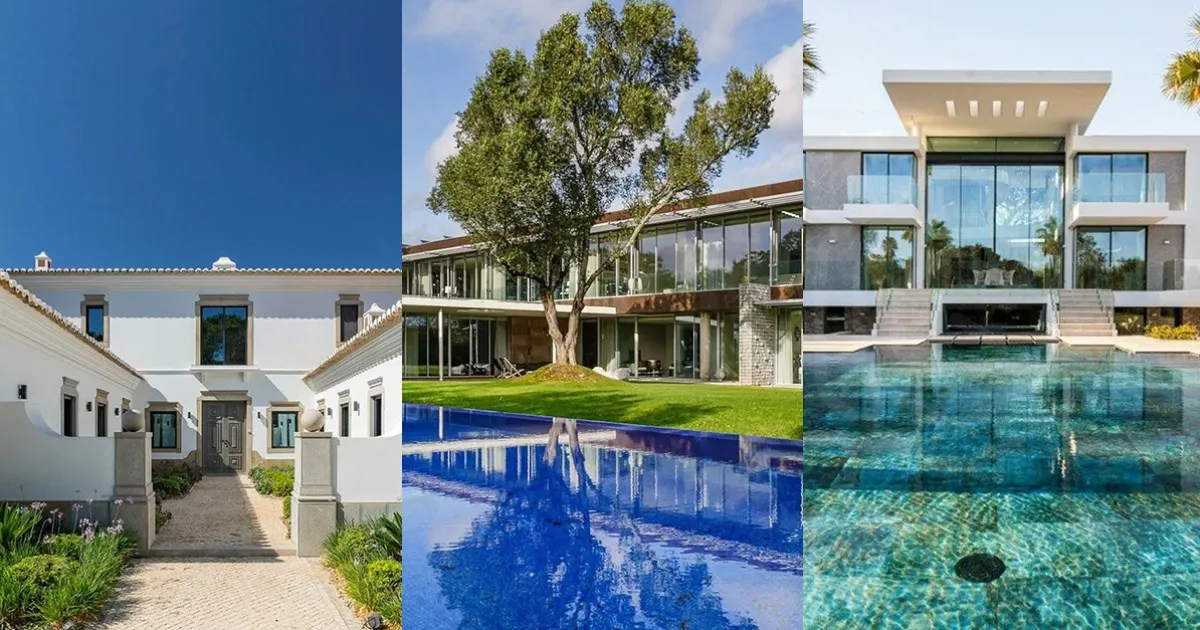
Take the Braga student accommodation project as an example. Located near the University of Minho, the project serves a clearly identifiable demand for accommodation from students, academic staff, and younger residents. From initial site selection, product positioning, and planning and design through to development and construction, each stage needs to be shaped around actual market demand. Once the project is completed, Golden Beach, a company within the Group, further participates in property and operational management. Through the ongoing management of occupancy rates, rental levels, operating costs, property maintenance, and other factors, the completed property can be transformed into an operational asset capable of generating cash flow.
The Group’s serviced apartment project in Oeiras reflects a different asset logic. Unlike the Braga project, which is primarily driven by student accommodation demand, the Oeiras project is designed for a more diverse range of potential residents and users, including young professionals working in Lisbon and surrounding areas, digital nomads, employees of nearby business and industrial parks, and business travellers. These groups have different requirements from traditional residential tenants, particularly in terms of flexible accommodation, transport accessibility, local amenities, and residential services. As a result, the project needs to incorporate its future operating model, service system, and real-life usage scenarios into product design and investment decisions from the development stage onwards. Different types of real estate respond to different forms of market demand and therefore require corresponding development positioning and operating models, ultimately converting genuine accommodation demand into occupancy, operating cash flow, and long-term asset value.
The value of a real estate investment is therefore not created at a single point when construction is completed. Instead, it develops throughout the entire lifecycle of the asset:
Project Acquisition & Positioning → Development & Construction → Asset Operations → Cash Flow Management → Asset Value Enhancement → Final Exit
Through its development and operating platforms, AsiaEuro Group participates in multiple stages of this lifecycle. This means that the Group’s approach to real estate investment does not end before capital enters a project, but can extend further into the process through which the underlying asset actually creates value.
7. Why Do We Emphasise Full-Cycle Asset Management from Investment to Operations?
For investors, the key consideration in a real estate investment is not simply whether the right project was selected at the outset, but whether the original investment rationale can be effectively carried through the entire process of development, operations, and exit once the capital has been deployed.
A project may begin with a clear investment thesis: Why this location? Who are the target users? Where does market demand come from? How is the project expected to generate cash flow? Yet between the initial investment decision and the final return, the project must still go through development and construction, product delivery, actual operations, and eventual exit. A significant deviation from expectations at any stage may affect the final investment outcome.
The first benefit of full-cycle asset management for investors is therefore to reduce the disconnect between investment decisions and the actual execution of the underlying assets. AsiaEuro Group is involved in fund management, real estate development, and asset operations, allowing investment decisions made at the fund level to extend into project development and day-to-day operations. Golden Meridian is responsible for fund management, the Group’s real estate development platform participates in project development and construction, while Golden Beach is further involved in the property and operational management of relevant assets.
The second benefit is that future operational requirements can be considered earlier in the investment and development process. Real estate ultimately serves real market demand. The Braga student accommodation project is designed around accommodation demand near the university, while the Oeiras serviced apartment project targets groups such as young professionals, digital nomads, employees of nearby companies and business parks, and business travellers. Different user needs influence product positioning, facilities, services, and operating models. For investors, this means that the project begins addressing a practical question from the development stage: Who will use the property once it is completed, and how will that demand translate into occupancy and operating cash flow?
The third benefit is that value management continues after the asset has been completed. For operational real estate, completion is not the end of investment management. Data and market feedback gathered through ongoing operations can help assess whether the original investment assumptions are being realised. Which customer groups are actually driving occupancy? Which types of units are most in demand? Are rental levels in line with expectations? Which operating costs are higher than originally estimated? These are factors that cannot be fully determined at the beginning of a project. Investment models provide expectations; operations provide real-world results.
AsiaEuro Group’s involvement across fund management, real estate development, and asset operations is therefore not simply about extending the business chain. The objective is to enable investors to understand returns from a full-lifecycle perspective from the outset, while creating greater continuity between investment decisions, project execution, actual operations, and asset value management. This means investors can understand not only where their capital is invested, but also how the project is expected to generate cash flow, whether its actual operating performance is consistent with initial expectations, and ultimately how the value of the asset may be realised.
Of course, full-cycle management does not eliminate investment risk. Rather, it brings more of the factors that can influence investment outcomes into an ongoing process of management and assessment. Once investors understand how an investment is expected to create value, the next equally important question is where that value may be affected along the way—and what risks investors ultimately need to bear.
8. What Are the Risks of European Asset Allocation?
European asset allocation does not automatically reduce overall investment risk simply by adding more countries, currencies, or asset classes to a portfolio. The factors discussed earlier—including interest rates, exchange rates, real estate cycles, financing costs, underlying asset performance, and liquidity—can all affect the final investment outcome. What matters is not simply how many risk factors exist, but whether those risks have been properly identified and whether they are aligned with the investor’s objectives and risk tolerance.
(1) Diversifying “Products” Does Not Necessarily Mean Diversifying Risk
The purpose of asset allocation is not simply to hold more investment products, but to avoid exposing different assets to the same underlying sources of risk.
For example, allocating part of a portfolio to a European fund and another part to European real estate may appear to represent two different types of investment. However, if both assets are concentrated in the same country, denominated in the same currency, or highly exposed to the same real estate cycle, the overall portfolio may still carry a significant degree of concentration risk.
Therefore, when allocating assets in Europe, investors should look beyond “how many different products” they own and consider European assets within the context of the family’s overall portfolio. Where is the family’s existing wealth primarily concentrated? Will the new investment increase or reduce existing risk concentration? Do the different assets genuinely complement one another in terms of geography, currency, investment horizon, and sources of return?
The purpose of diversification is not to make a portfolio more complicated, but to prevent family wealth from becoming overly dependent on a single market or source of risk.
(2) Investment Returns Cannot Be Compared by Looking at a Single Percentage
When comparing European funds, real estate, or other investment opportunities, expected returns are often the easiest figures for investors to compare directly. In practice, however, two apparently similar return figures may be based on very different calculations and may depend on very different conditions.
For example, the return presented for a real estate project may come from rental cash flow, but it may also include potential capital appreciation from the future sale of the asset. Fund returns may come from the operating performance of underlying assets, project exits, or distributions to investors. It is also important to determine whether the return shown is a gross return or a net return after management fees, operating costs, and other expenses, as well as whether returns are distributed annually or can only be realised when the underlying asset is eventually exited.
For funds or real estate investments that need to be held for several years, the timing of returns is equally important. An investment may be expected to generate a relatively high overall return, but if most of that return depends on the sale of a project several years later, its cash flow profile will be very different from that of an asset capable of generating stable annual distributions.
(3) The Actual Performance of Underlying Assets May Differ from Expectations
Whether investing through a fund or directly in real estate, expected returns ultimately depend on the actual performance of the underlying assets. A fund may have a well-established management, custody, and audit structure, but this does not eliminate investment risk. For funds investing in real assets, factors such as project development, market demand, operating performance, and the eventual exit can all affect the final investment outcome.
For example, the expected return of a real estate project may initially be calculated based on projected construction costs, rental levels, occupancy rates, and future asset values. During implementation, however, higher construction costs, project delays, changes in market demand, lower-than-expected occupancy, or rising operating expenses may cause actual cash flows and investment returns to differ from initial projections.
For investments backed by real assets such as property, fund-level management and project-level execution are equally important. The fund structure determines how capital is managed, while the ability of the underlying assets to create value as expected ultimately forms the foundation for achieving investment returns.
9. Why Does Asset Allocation Still Matter When Investing for European Residency?
For some Asian families, European residency planning may be what first introduces them to European funds or other cross-border investments. This type of investment differs from conventional international asset allocation in one important respect: when selecting an investment, investors need to consider not only its potential returns and risks, but also whether it meets the requirements of the relevant residency programme.
This means that residency requirements may place certain boundaries on investment choices. Eligible investment types, minimum investment amounts, holding periods, and exit timing may all be influenced by applicable policies and programme requirements. Investing for residency purposes is therefore not exactly the same decision-making process as allocating assets purely to maximise investment returns.
However, a different investment objective does not change the risks associated with the capital itself. Even if an investment meets residency requirements, investors still need to understand who manages the fund, where the capital is ultimately invested, how returns are generated, what risks may arise, and whether the exit mechanism is clearly defined. “Meeting residency requirements” determines whether an investment can serve a residency objective, while “asset allocation” determines whether the investment itself makes financial sense.
For investors, the more practical approach is not to choose between “residency” and “investment”, but to evaluate available options through an asset management lens within the boundaries created by residency requirements. Even when European residency is the original reason for investing, the investment should still, as far as possible, be aligned with the investor’s risk tolerance, investment objectives, and overall asset structure.
Residency may be the starting point for an investment, but once capital is invested, the risks still need to be managed according to sound investment principles.
10. How Can You Build a European Asset Allocation Strategy That Fits Your Needs?
The first step is to clarify why European assets are being considered and what role they are expected to play within the family’s long-term planning. For many cross-border families, interest in European assets does not arise solely from investment considerations. It may also be connected to European residency, children’s education, future living arrangements, or broader long-term family planning. In such cases, residency planning may provide the initial reason for entering the European market, but the investment itself should still be assessed independently.
For example, when a family needs to make a significant investment as part of its European residency planning, the more important questions become: which assets should this capital be allocated to? How long will the capital need to remain invested? While meeting the relevant planning requirements, how can the family also balance risk, return, liquidity, and the eventual exit?
Building a European asset allocation strategy therefore requires an understanding of how the family’s existing assets are currently distributed across countries, currencies, and asset classes, as well as whether there may be future financial needs related to living in Europe, education, business activities, or other purposes. On this basis, the family can then determine what role European assets should play within the overall portfolio—for example, increasing exposure to euro-denominated assets, achieving greater geographic and currency diversification, or allocating capital across real estate, funds, and other types of assets.
A truly comprehensive plan is one that finds the intersection between residency, family, and investment needs, allowing capital that originally entered Europe as part of residency planning to also be allocated according to sound asset management principles.
11. European Asset Allocation: Frequently Asked Questions
(1) What Is the Minimum Amount Required for European Asset Allocation?
There is no universal minimum investment amount for European asset allocation. The specific threshold depends on the asset class and investment method selected. Equities, ETFs, and certain public market funds can be accessed with relatively small amounts of capital, while real estate, private funds, and real estate funds generally require higher minimum investments.
The more important question is therefore how much of the family’s assets should be allocated to Europe and whether that proportion is appropriate within the overall family portfolio.
(2) Does European Asset Allocation Require Investing in Real Estate?
Not necessarily. Real estate is only one of the available options for European asset allocation. Depending on their needs, investors may also consider equities, bonds, investment funds, private equity, infrastructure, and other asset classes.
For investors who want exposure to the European real estate market without directly purchasing and managing properties, real estate funds can also provide an indirect way to invest. These approaches can differ significantly in terms of investment horizon, liquidity, management requirements, and risk.
(3) What Is the Difference Between Investing in a European Fund and Directly Purchasing European Real Estate?
Direct real estate investment means that the investor owns a specific property. Investment performance is primarily influenced by factors such as local property prices, rental income, property operations, and transaction costs, while the investor will also typically need to take responsibility for the corresponding property management.
When investing through a fund, capital is managed by a professional fund management company in accordance with an established investment strategy and allocated to the relevant underlying assets. Investors hold units or shares in the fund rather than directly owning the underlying properties. A fund may invest in multiple projects and may adopt different development, holding, or exit strategies.
(4) If a European Fund Is Regulated, Does That Mean the Principal and Returns Are Guaranteed?
No. Regulatory oversight and guarantees of investment principal or returns are two entirely different concepts.
Regulation establishes requirements relating to areas such as fund establishment, management, disclosure, asset custody, and investor protection. However, a fund remains a financial investment. Its ultimate performance may be affected by market conditions, the fund’s strategy, the performance of its underlying assets, management capabilities, and exit conditions. Investors therefore remain exposed to the corresponding investment risks.
(5) What Role Does AsiaEuro Group Play in European Asset Allocation?
AsiaEuro Group’s activities are not limited to a single investment product. They extend across different stages of the asset value chain, including fund management, real estate development, and asset operations.
Within the Group’s existing business structure, Golden Meridian performs fund management functions, the Group’s real estate development platform participates in the development and construction of relevant real asset projects, and Golden Beach participates in property and subsequent operational management.
These businesses operate at different stages of the asset value chain, allowing the Group’s involvement to extend from investment management at the fund level to the development and operation of underlying real assets.
(6) Do AsiaEuro Group’s Funds Invest Only in the Group’s Own Real Estate Projects?
Not necessarily. The specific investment scope and strategy of each fund are determined by its official fund documentation. The fund management company is required to make investment decisions in accordance with the established investment strategy and applicable regulatory requirements.
Real estate projects developed with the participation of the Group represent only part of the potential universe of underlying investment opportunities. This does not mean that a fund automatically has an investment relationship with any particular project developed by the Group.
(7) Why Does AsiaEuro Group Participate in Fund Management, Real Estate Development, and Asset Operations?
For real assets such as real estate, an investment is not complete at the moment of “acquisition.”
Fund management determines how capital is invested and managed; real estate development determines how an investment plan is transformed into a physical asset; and subsequent operations further influence occupancy rates, cash flow, maintenance costs, and the asset’s long-term performance.
AsiaEuro Group’s involvement across these areas is not simply about placing different businesses under the same structure. The objective is to establish an integrated value chain extending from investment management to the development and operation of underlying assets. This is what we refer to as “full-cycle asset management.”
(8) If a Family Is Considering Both European Residency and Asset Allocation, Which Should Be Planned First?
It depends on the family’s primary objective. If European residency is a clear priority, the investment must first meet the relevant legal and policy requirements. This may limit the range of eligible investments, investment horizons, and liquidity options, and may not necessarily result in the same asset allocation that would be chosen under completely unrestricted investment conditions.
Investing for residency purposes does not mean that the investment itself should be overlooked. A more balanced approach is to compare the underlying assets, risks, expected returns, and exit mechanisms within the range of investments that meet the residency requirements, seeking an appropriate balance between residency objectives and investment quality.
For cross-border families, the real question is therefore not simply “Should residency planning come first, or should investment planning come first?” Instead, both should be considered within the same long-term family strategy from the outset: What investment conditions need to be met for the residency plan? Where should the capital be allocated? How long will it need to remain invested? How do the underlying assets generate returns? And how can the investment eventually be exited?
If you are considering European residency, European fund investment, European real estate investment, or other forms of cross-border asset allocation, AsiaEuro Group can help assess your European asset allocation needs based on your family’s existing asset structure, available capital, and future plans, taking into account both investment objectives and long-term family considerations, including:
- Assessment of your existing asset structure and European asset allocation needs
- Introduction to European funds, real estate, and other investment approaches
- Analysis of fund structures, management mechanisms, and underlying assets
- Understanding real estate development, operations, and investment logic
- Assessment of investment horizons, risks, cash flow, and exit mechanisms
- European Residency × Assets × Long-Term Family Planning
Contact AsiaEuro Group today to book a one-to-one consultation and start planning a European asset allocation strategy tailored to you and your family.